
Key Takeaways
- Cross-border cash pressure usually comes from timing gaps, currency mismatches, and unclear fees.
- A rolling 13-week forecast makes potential shortfalls easier to identify before they become urgent.
- Matching revenue and expenses in the same currency can reduce unnecessary conversions.
- Settlement speed, total cost, payment tracking, and reconciliation all matter when comparing payment routes.
- Clear approval rules and supplier verification procedures help protect cash and reduce the risk of fraud.
International sales, overseas suppliers, and remote contractors can help a small business grow, but they also complicate everyday cash management. A multi currency account for business can be one part of an organized setup, especially when the company needs to receive, hold, and pay funds in more than one currency.
The larger goal is visibility. Business owners need to know how much cash is available, when incoming payments will settle, which currency each obligation requires, and how fees affect the amounts received or paid.
Why Cross-Border Cash Flow Needs Attention
International activity is no longer limited to large corporations. Recent research on international sourcing by U.S. small businesses found that 57% of surveyed small and medium-sized firms purchased goods or production inputs from overseas suppliers. That activity brings foreign exchange, settlement timing, supplier liquidity, and payment controls into routine operations.
Profit is not the same as available cash. A design agency may have a healthy sales pipeline, yet still face a shortage if a client pays in 45 days, while overseas contractors need payment within seven days. The business can be profitable on paper and still struggle to meet the next obligation.
Where Cash Flow Breaks
Cross-border cash flow often fails at predictable pressure points:
- Collection delays: A customer may pay on time, but the funds may not be available immediately.
- Currency mismatches: Revenue may be received in euros, while payroll and rent are due in U.S. dollars.
- Hidden costs: Transfer charges, intermediary deductions, and exchange-rate spreads can reduce the final amount.
- Time zone and banking cutoffs: A late-day instruction may move to the next business day.
- Compliance reviews: A provider may request documents before releasing a transfer.
- Poor visibility: Balances scattered across accounts, cards, wallets, and processors make it harder to see how much usable cash you have.
Build A Multi-Currency Forecast
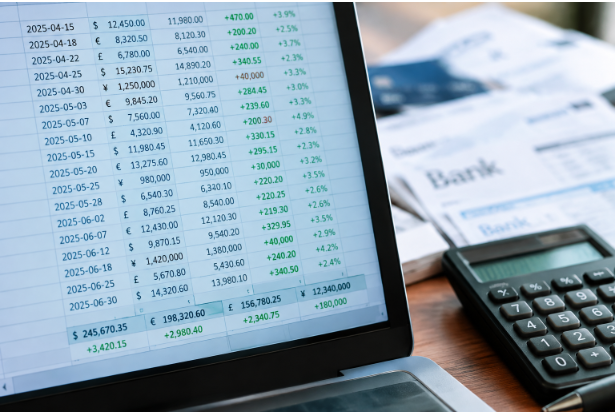
A spreadsheet is enough to start. Use a rolling 13-week view and update it weekly. For each week, record:
- Opening cash by currency.
- Expected customer receipts, including customer, invoice number, currency, amount, and expected settlement date.
- Expected supplier payments, payroll, tax obligations, and recurring expenses.
- Whether each item is confirmed, likely, or uncertain.
- The exchange rate assumption is used when translating amounts into the company’s reporting currency.
- Expected closing cash by currency and in total.
Compare the forecast with actual results every week. If receipts routinely settle later than expected, revise the assumption instead of relying on the invoice due date alone.
Reduce Foreign Exchange Leakage
Currency management should support operations, not become speculative trading. Where practical, use foreign-currency revenue to pay expenses in that same currency. This can reduce the number of conversions and preserve flexibility when exchange rates move.
- Set a rule for when balances should be converted.
- Review the full cost of a transfer, not only the advertised fee.
- Avoid frequent small conversions unless the business need justifies them.
- Build a reasonable currency buffer into international pricing and budgets.
- Discuss whether supplier agreements should use a fixed currency or a pricing adjustment clause.
When comparing options, consider the exchange rate, transfer fee, amount the recipient receives, and expected settlement time together.
Choose The Right Payment Route
Different transactions call for different payment methods. Bank transfers can suit larger supplier payments, while cards may work for routine purchases where acceptance is available. Local payment rails may be useful when a customer or supplier prefers domestic methods. Digital wallets can help with smaller payments, provided the business can track transactions and reliably withdraw funds.
Stablecoin settlement may offer speed in some payment corridors, but businesses should carefully assess provider controls, custody, conversion, accounting treatment, and applicable requirements before using it.
For every route, ask:
- How long does settlement usually take?
- What is the total cost from sender to recipient?
- Can the payment be tracked if something goes wrong?
- What happens if it is rejected or delayed?
- Can it be matched easily to the correct invoice?
Set Clear Payment Rules
Written policies prevent rushed decisions. Set approval limits, require an additional review for new suppliers or unusual requests, and define who may approve currency conversions. Invoices should clearly state the currency, due date, payment instructions, and any late-payment terms.
Supplier bank details deserve special attention. The FBI advises businesses to use a secondary channel to verify changes to account information, so confirm any new payment instructions using a trusted phone number or a known contact rather than replying to the original email.
Improve Reconciliation And Reporting
Assign a reference number to every invoice and payment. Record the original currency, translated reporting value, exchange rate used, and any fees separately. Reconcile unsettled items at least weekly, then review aged receivables by customer, country, and currency.
A useful monthly report includes total receipts, total payments, conversion costs, delayed or rejected transactions, outstanding invoices, and cash balances by currency.
Common Mistakes To Avoid
- Forecasting only in one currency and overlooking currency-specific shortages.
- Treating a payment date as the same date cash becomes usable.
- Choosing a provider only because it appears faster.
- Leaving small balances spread across too many tools.
- Converting every incoming payment immediately without considering upcoming expenses.
- Having no backup route for a rejected or delayed payment.
- Mixing personal and business payment activity.
A Simple 30-Day Action Plan
Week One: Map The Current System
List every account, card, wallet, and processor. Record currencies, fees, limits, settlement times, and the three largest sources of delay.
Week Two: Create The Forecast
Build the 13-week view, separate confirmed receipts from estimates, and test what happens if a major customer pays late or a currency moves against the business.
Week Three: Set The Controls
Document approval limits, conversion guidelines, minimum cash buffers, and supplier-verification procedures.
Week Four: Review And Improve
Compare forecast costs with actual costs, remove unused payment routes, strengthen invoice terms where collections are slow, and select a few monthly measures to monitor.
Conclusion
Cross-border cash flow does not have to become a daily puzzle. A realistic forecast, sensible currency rules, dependable payment routes, and accurate records give a small business more control over how cash moves. The best setup is the one that makes funds easier to see, use, and reconcile.
Read More : Business Owners: Key Considerations When Ordering Custom Towels